
App template
Amortly: a lending & loans app template.
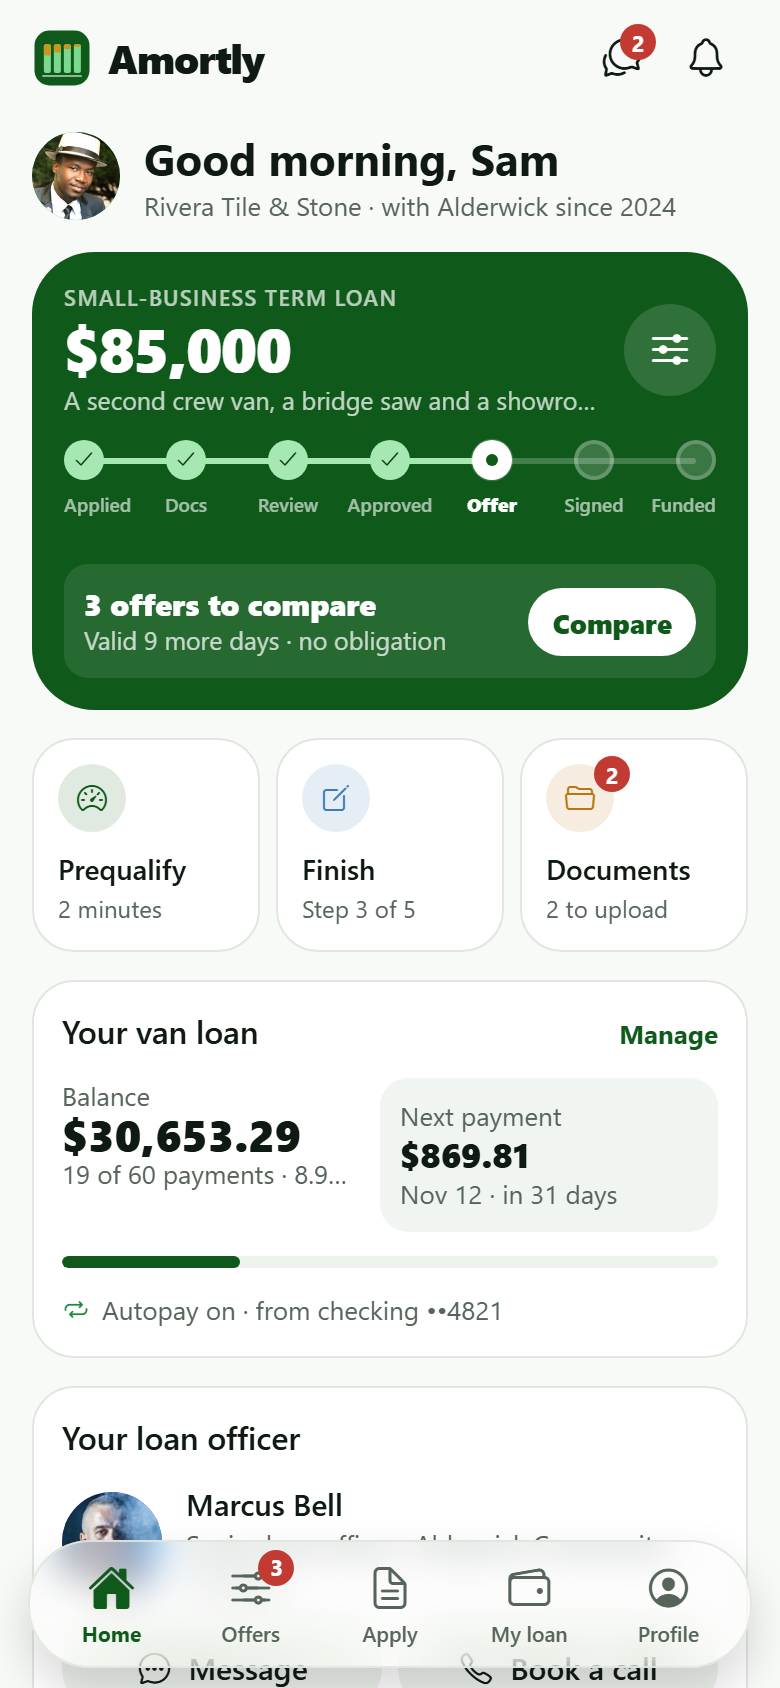
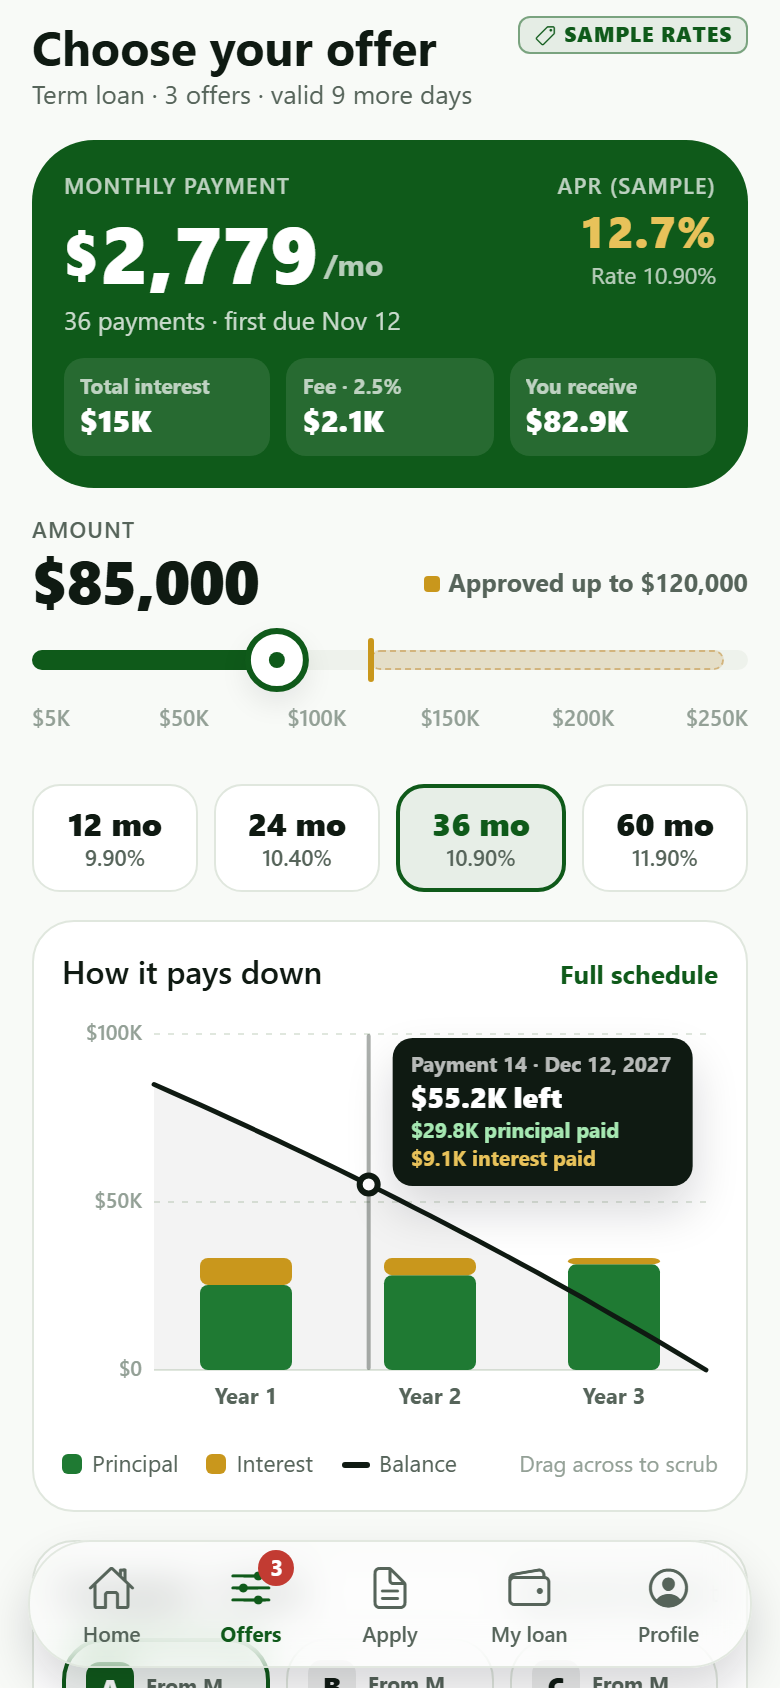
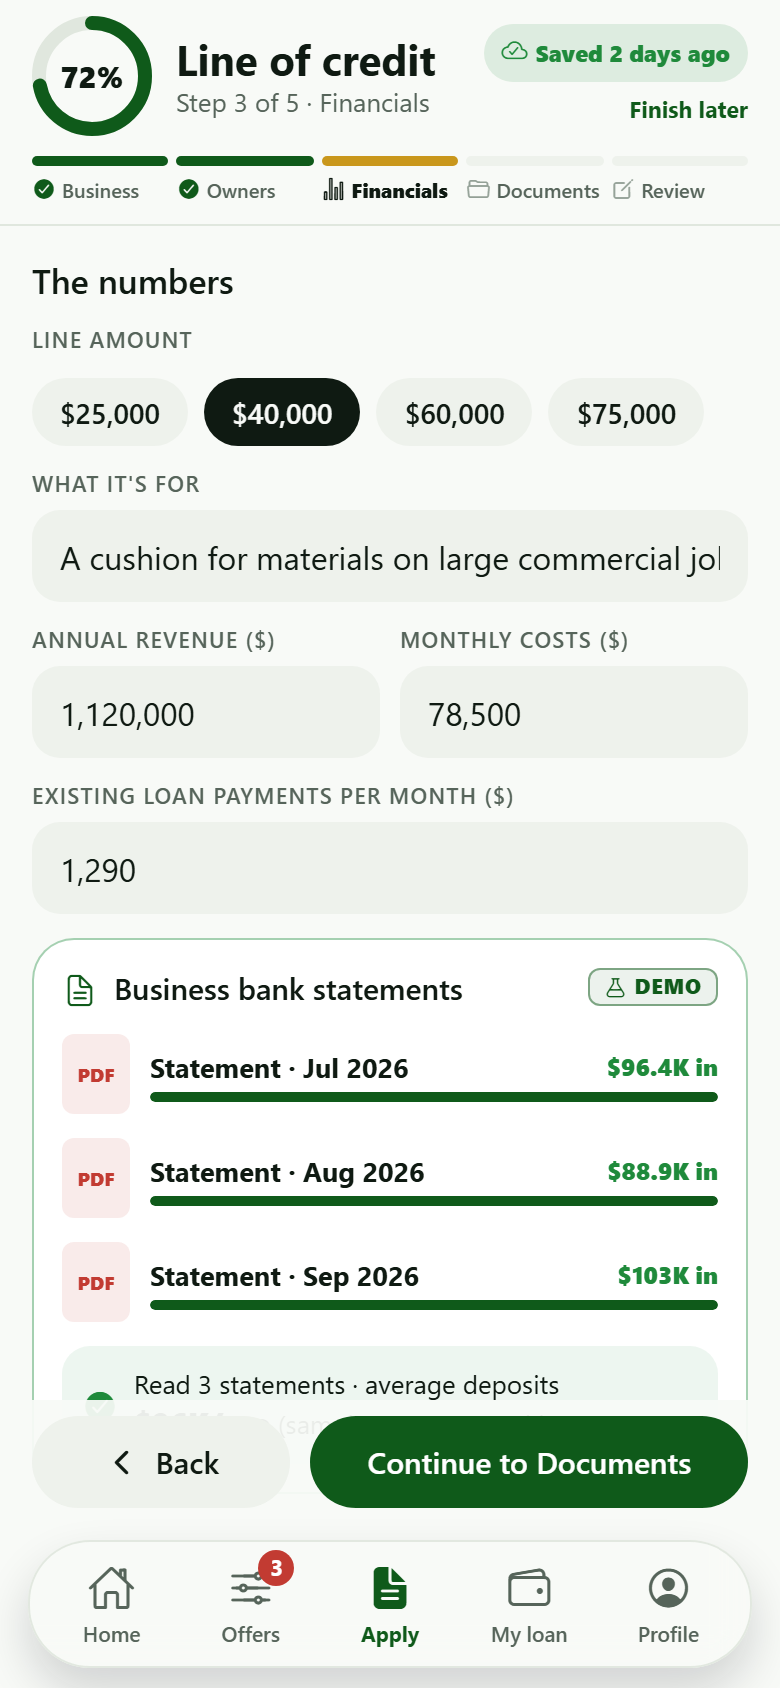
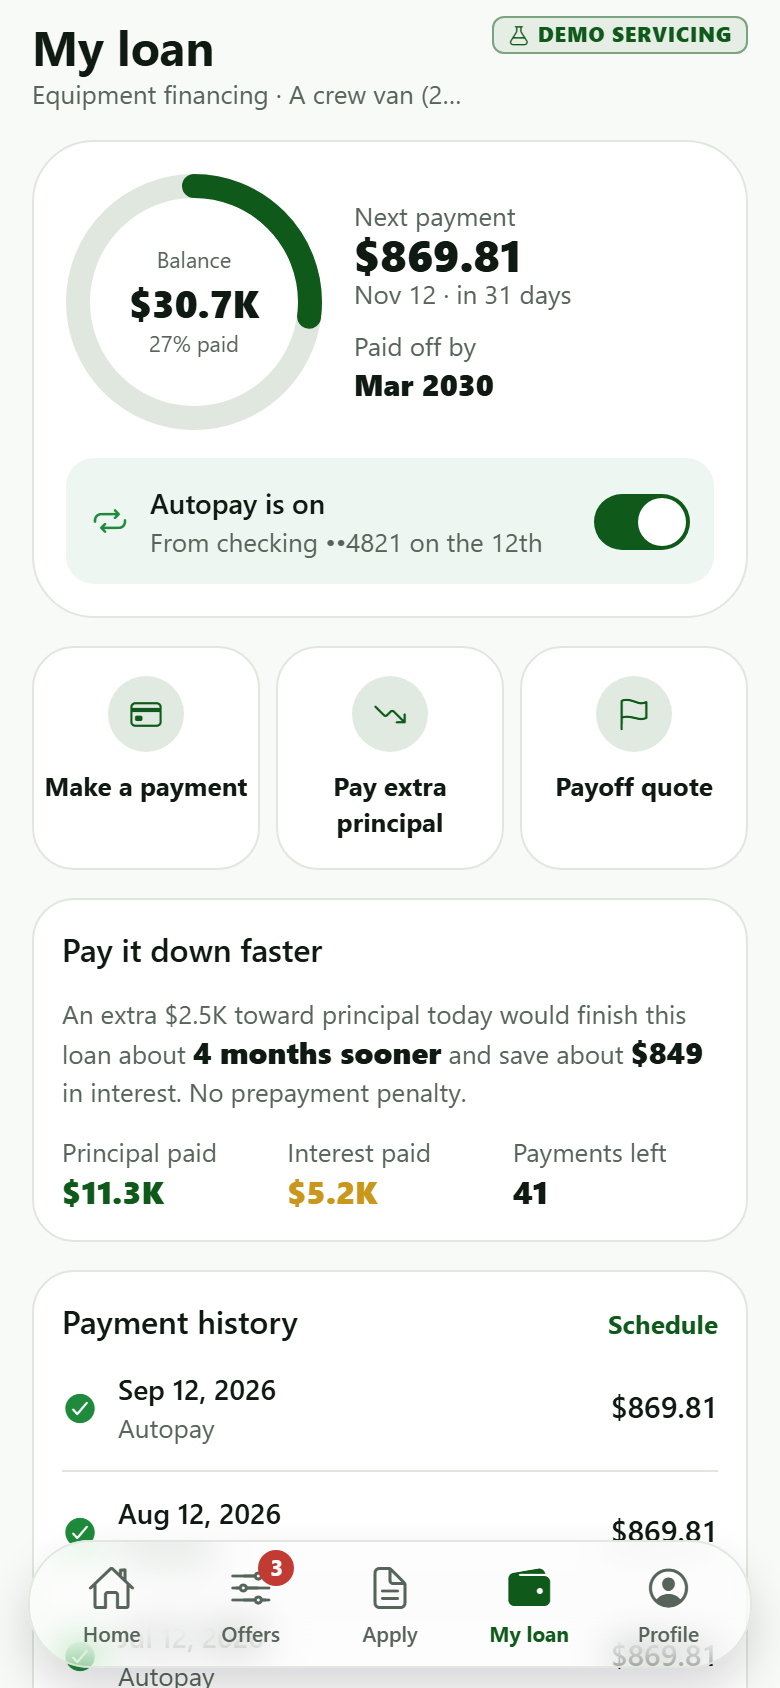
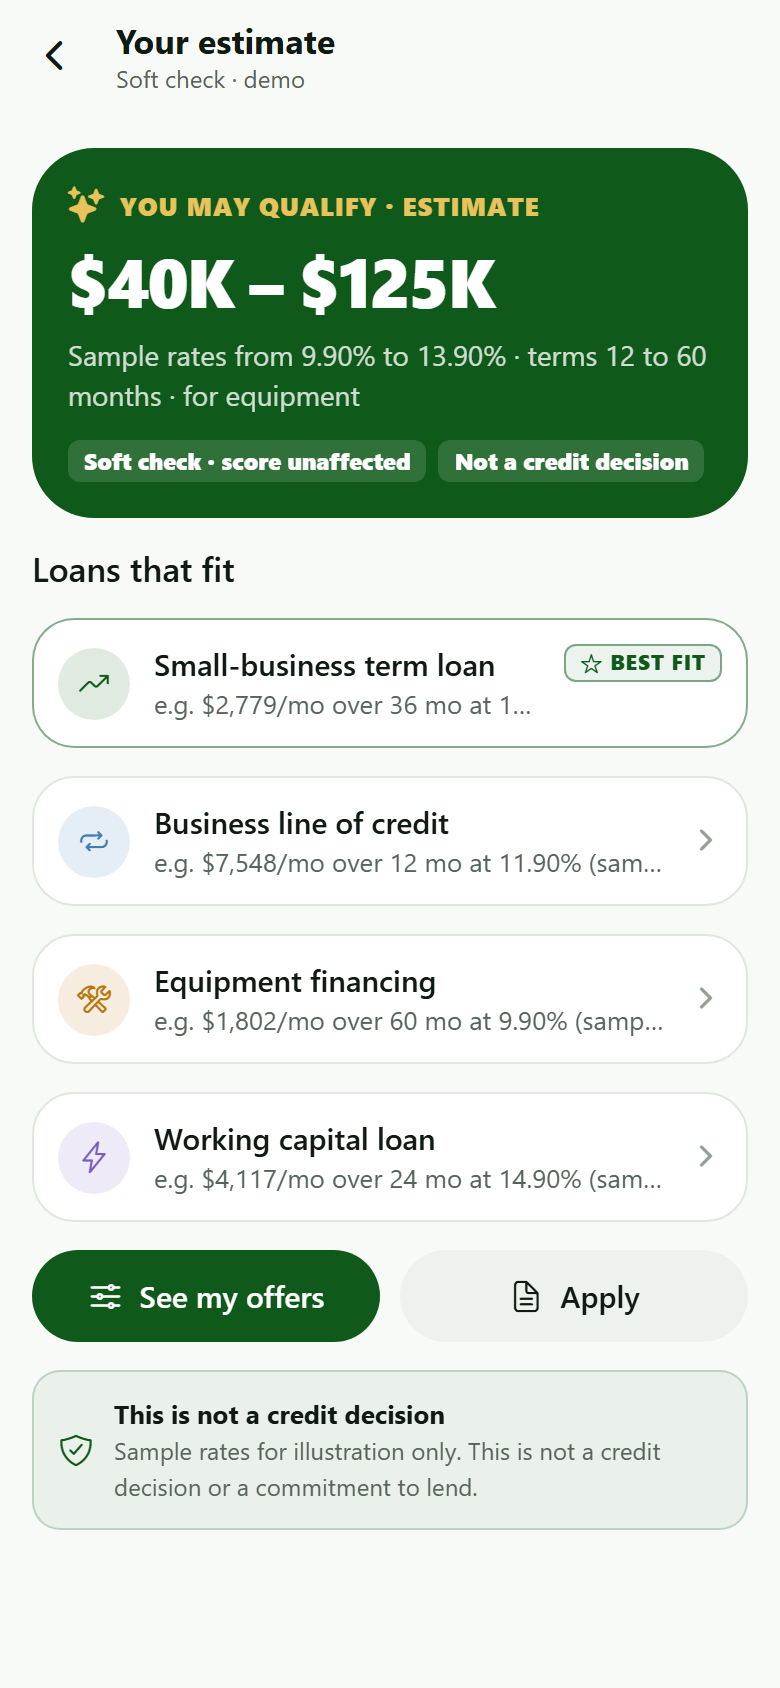
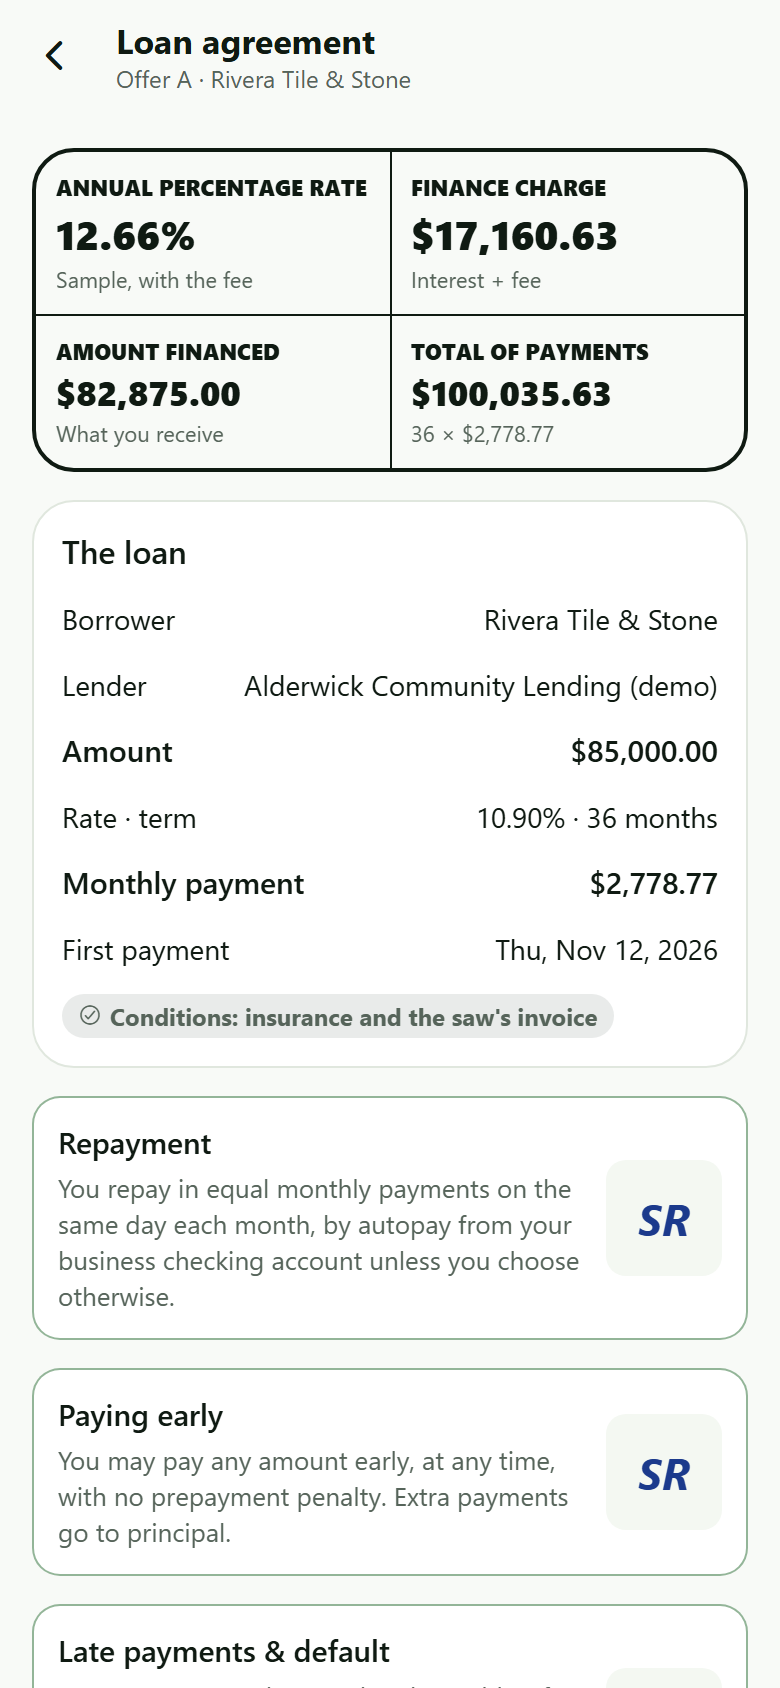
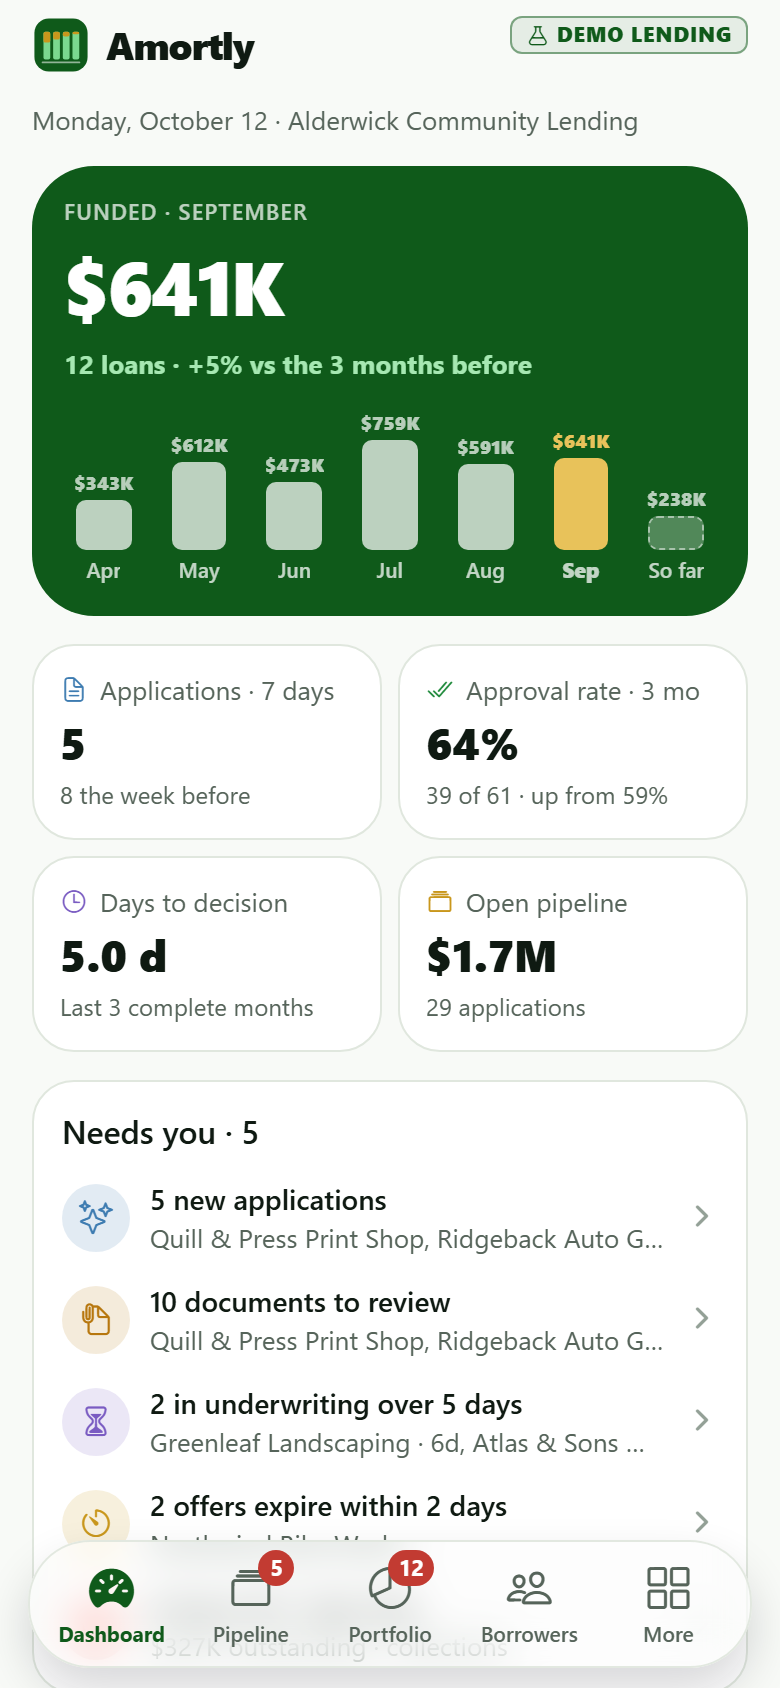
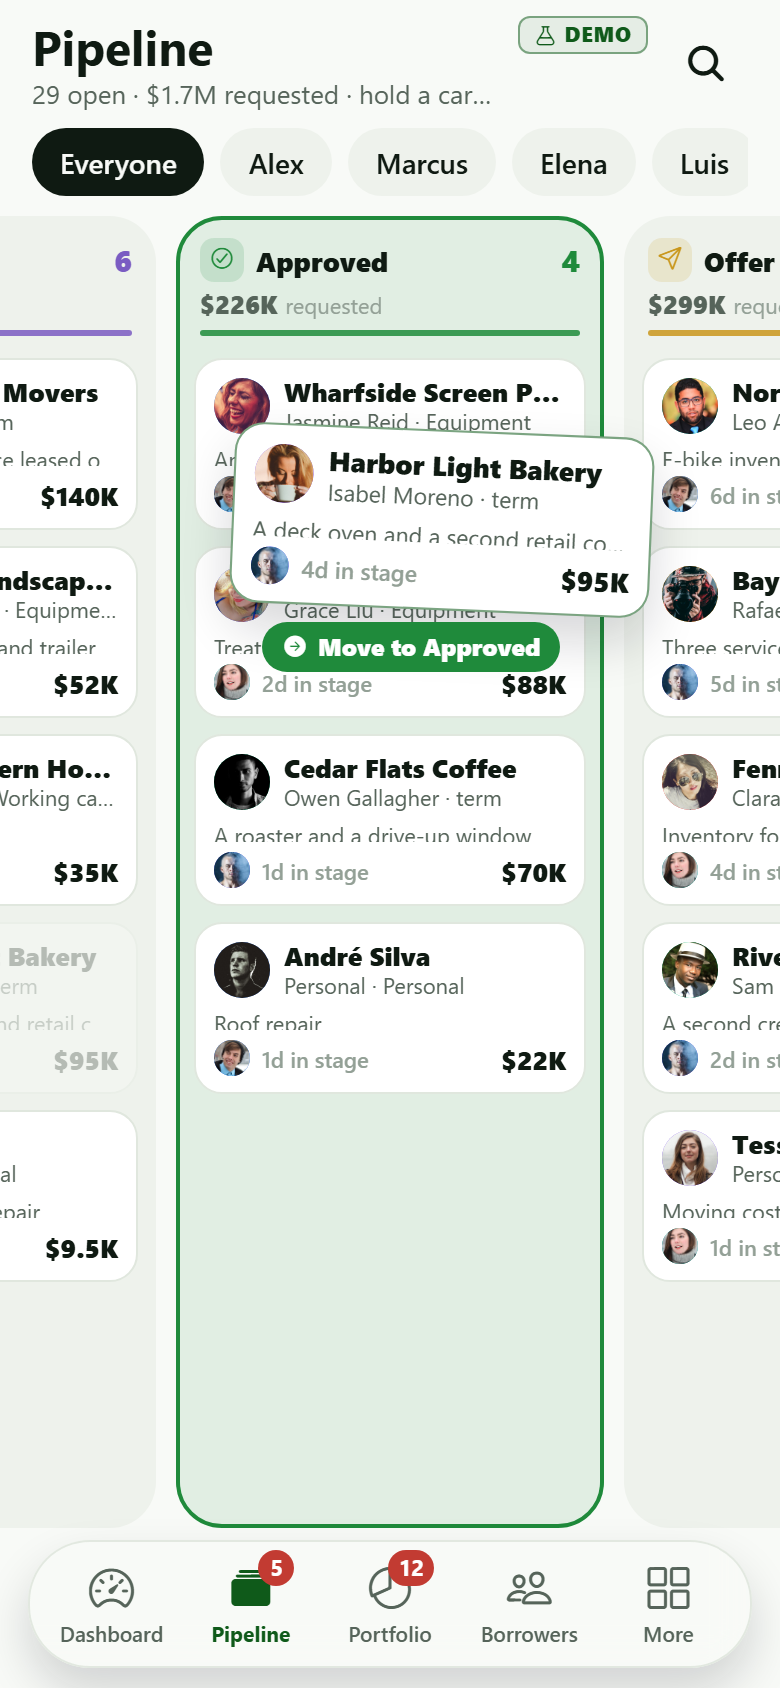
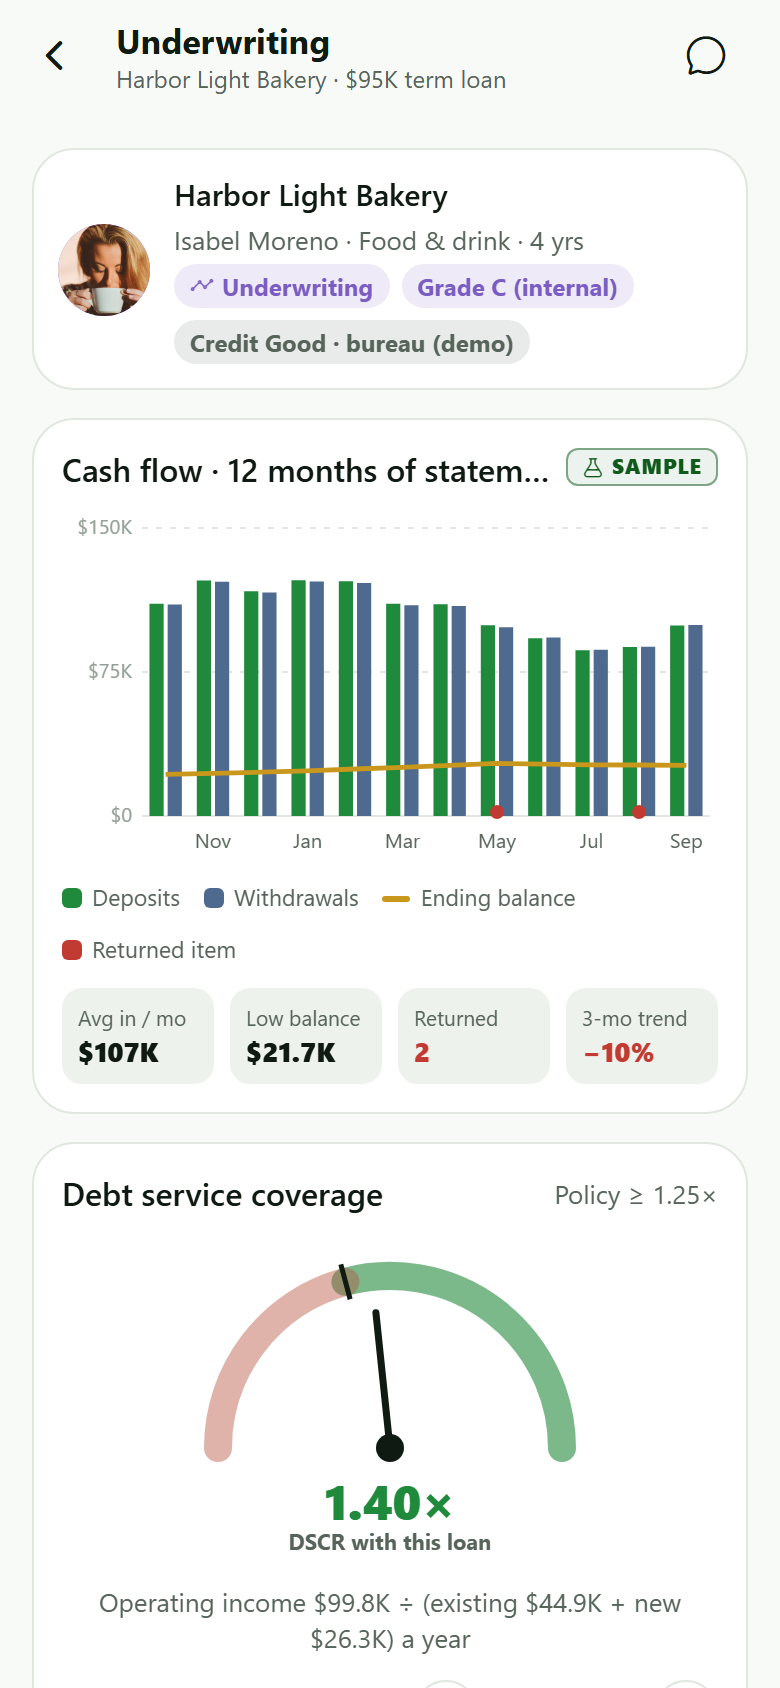
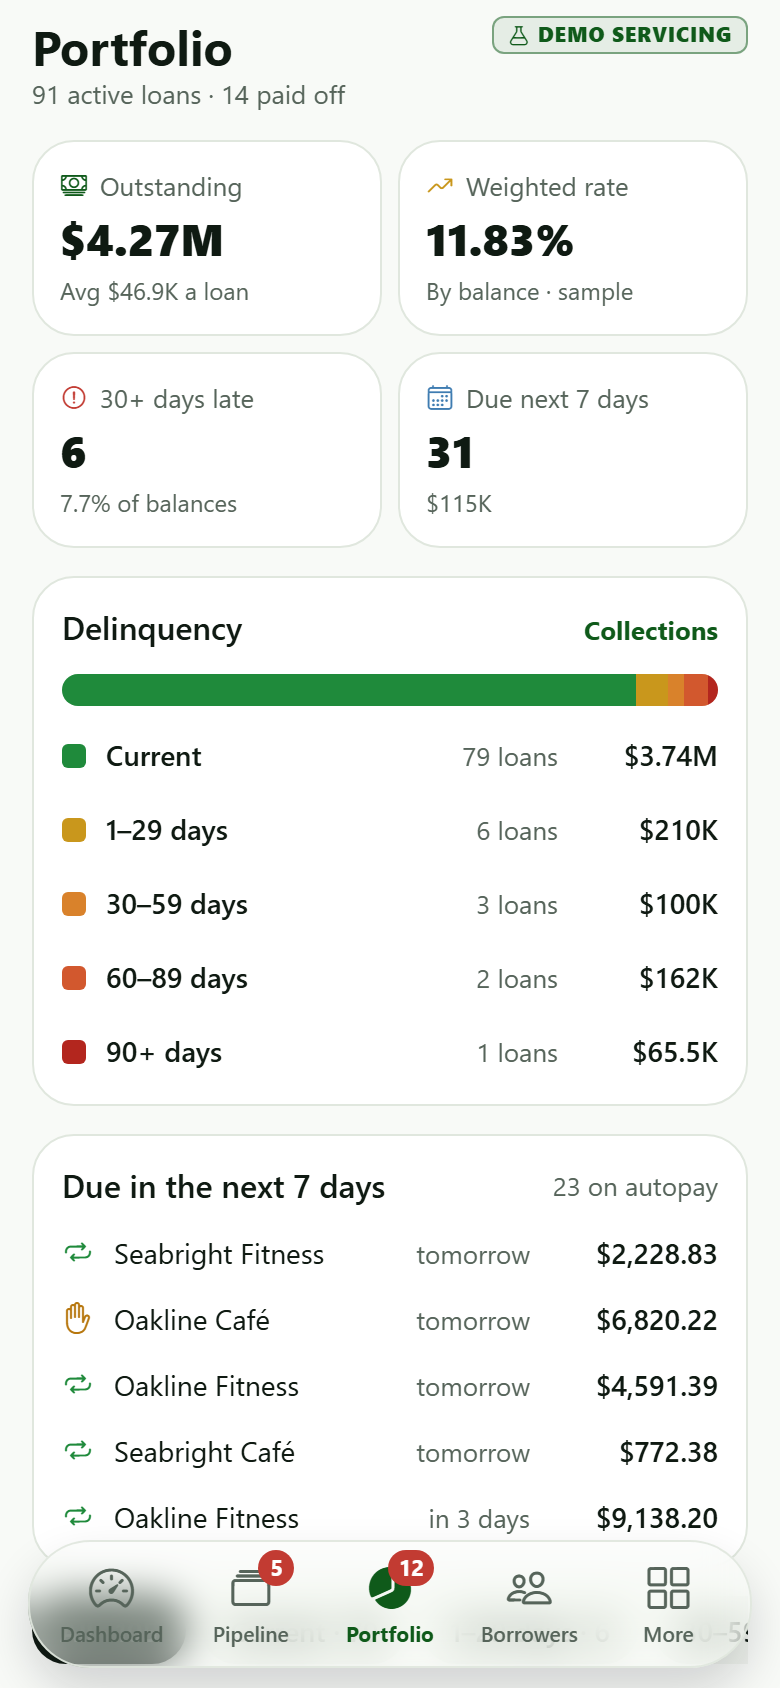
A community lender's app with both sides in one: the borrower's loan app and the lender's pipeline, underwriting and servicing. Demo lending throughout: every rate is a sample for illustration, prequalification is a soft check with "a credit bureau (demo)", nothing is a credit decision, account numbers are masked, e-signatures are labelled demo and payments end on a "Demo payment" receipt. The borrower opens on the offer slider: drag a big amount slider from $5,000 to $250,000 (the approved amount is a gold tick, past it the track turns amber) and pick 12, 24, 36 or 60 months, and the monthly payment rolls digit by digit, the total interest, fee, money received and APR (sample) update, and an amortization chart, principal and interest stacked per year with the remaining balance as a line, redraws on the UI thread while the finger moves; scrub the chart month by month for the balance and what has been paid; compare up to three offers side by side (lowest payment and least cost tagged), save your own terms to compare, and choose one. The application stepper takes a business through Business, Owners, Financials (three months of bank statements uploaded and read, staged), Documents and Review & e-sign, with a progress ring that fills as the form does and a "Saved, finish later" pill; submitting puts a card in the lender's New column in the same session. Around them: a home with a seven-step tracker (Applied → Funded) and the next thing to do, prequalify in two minutes (amount, purpose, the business, a soft check with staged steps, then an estimated range and the loans that fit), loan products with sample rate tables and example payments, a document checklist with conditions of approval and a staged scanner that traces, captures and reads the page, the loan agreement as a plain-language disclosure box with tap-to-initial sections and a drawn signature, a funding tracker, a loan dashboard after funding (balance ring, next payment, autopay, a payoff quote with per diem, extra principal that shows the months and interest it saves, payment history), the full amortization schedule, messages with the loan officer, notifications, search with answers, profile, edit profile and settings. The lender's side (Profile → "Lender", or sign in as Alex Chen): a dashboard (funded volume in the last complete month over six complete months, applications in a rolling seven days, the approval rate over three complete months, days to decision, the open pipeline, what needs a person, the funnel, team workload and the portfolio); a pipeline board of eight stages (New → Docs needed → Underwriting → Approved → Offer sent → Signed → Funded / Declined) where a held card lifts and is dragged to another stage, with rolling counts and dollar totals; the application record (move stage, accept or send back uploads, offers and the borrower's choice, conditions, messages); an underwriting workspace with twelve months of statement cash flow, a DSCR (or DTI) gauge that moves as amount and term change against the policy line, risk flags to clear, and a decision with conditions or a counter; an offer builder that sends straight to the borrower's offer slider; document requests that land on the borrower's checklist; the funded-loan portfolio with delinquency buckets (current, 1–29, 30–59, 60–89, 90+), payments due this week and loan records; payments & collections with reminders and promises to pay; borrowers list and record; products & pricing with rate ranges, fees and credit policy. 32 screens on seeded tables: 8 team, 5 products, 194 borrowers, 155 applications, 224 documents, 17 offers, 101 loans, 387 payments, 25 messages.
32 screens, real flows
Make it yours by describing it
Tell Co-Create what to change, in plain words or a voice note. It asks what it needs to know, then shows you designs before anything is built.
Nothing changes until you approve
Approve one piece or a whole section. Every build gets a preview, and you can roll back to any earlier point.
Your app, your code
Go live on a clean address or your own domain, and download the full source whenever you like.
Your idea could be an app by Friday.
Start free. Talk it through, answer a few questions, pick a design and watch it build.
7 days freeCancel anytime